
Retirement Planning with Charitable Gift Annuities
Introduction
For many individuals, at various stages of their careers, retirement planning is an important topic of interest. For those who are charitably minded, charitable gift annuities (CGAs) can serve as a valuable tool for planning and enhancing retirement security. With CGAs, donors can make significant charitable contributions that provide them with tax advantages while securing a fixed income stream. Since CGAs can be tailored to different financial and charitable goals, CGAs can serve as a versatile option for retirement planning.
What is a Charitable Gift Annuity?
A CGA is a contract between a nonprofit and a donor. The donor transfers cash or appreciated property to the nonprofit and, in return, the nonprofit promises to pay a stream of income for the duration of one or two lives. All the assets of the nonprofit, including its endowment and real property, stand behind the nonprofit’s promise to pay the gift annuity.
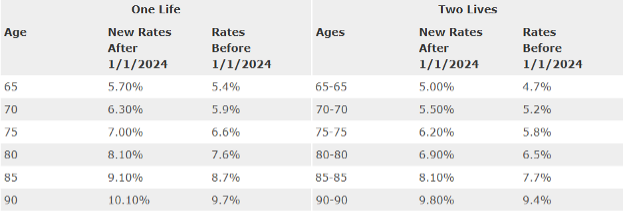
The American Council on Gift Annuities (ACGA) is a nonprofit organization that provides suggested CGA rates based on the annuitants’ ages. These rates are periodically adjusted to reflect the market conditions and changes in life expectancy. In 2024, the rates for CGAs were increased, making them an appealing option for your financial planning:
CGA Taxation
A CGA is treated as a bargain sale. This is because part of the transaction is a gift to the nonprofit and part of the asset is a return of value to the donor, with the charitable deduction based on the gift portion to the nonprofit. The payments to the annuitant can be structured for a monthly, quarterly, semiannual or annual basis, with each payment consisting of partially tax-free payouts. When dealing with an appreciated asset that is used to fund a CGA, the capital gain on the gift portion is bypassed and the capital gain attributed to the annuity portion is recognized over the donor’s lifetime, provided the donor is the annuitant.
IRA owners 70½ and older can benefit from a once-in-a-lifetime Qualified Charitable Distribution (QCD) from an IRA to fund a charitable gift annuity up to $54,000. Certain conditions will apply for QCD-funded CGAs. The payout rate to the annuitant must be 5% or higher, and the contract cannot be assignable back to the charity. Additionally, the lifetime income must only benefit the IRA owner, the IRA owner’s spouse or both. Unlike CGAs funded with cash, there is no charitable deduction, and all payments made to the annuitants must be taxed as ordinary income.
Example A
Lindsay, a 72-year-old who is about to retire, has a primary retirement account but wants to make sure she will have enough income once she stops working. She holds stock from a major tech company, which she bought for $25,000 and is now worth $50,000. Knowing that selling the stock would require her to recognize $25,000 in capital gains, she decides to contribute the appreciated stock to her favorite local nonprofit in exchange for a charitable gift annuity. This approach not only provides her with a stream of income for life, but it also helps her manage and defer some of the capital gains tax.
Given her age, Lindsay qualifies for a 6.6% payout rate, which produces an annuity of $3,300. With this approach, she receives a charitable deduction exceeding $19,500, which results in tax savings of over $1,000. By funding the CGA with appreciated stock, she partially avoids the $25,000 in capital gains, bypassing the portion attributable to the charitable gift.